House View

House View Q4 2026: Renewed momentum

Our view of global markets

  • The global outlook has brightened. Despite persistent headwinds and above-target inflation, growth has remained resilient. The US appears set to reaccelerate from a solid base, European growth is outpacing expectations, and China could rebound in Q4.
  • The stronger growth backdrop allows central banks to stay focused on inflation as markets and economies adjust to higher rates. Following September hikes, we expect the US Federal Reserve (Fed), European Central Bank (ECB) and Bank of Japan to raise rates by a further 25 basis points each by year end.
  • Strong earnings, supported by investment and AI-related spending, should sustain momentum and support both equities and bonds. Bond yields are moving higher but, given the scale of energy-driven inflation, the adjustment remains orderly. Earnings continue to support credit spreads, while a higher-rate environment may favour cash-generating businesses and value stocks.
  • Amid solid growth and above-target inflation, markets expect forceful central bank action. After Kevin Warsh's unsettled start as chair, the Fed’s independence may need reinforcement. Any hesitation risks reigniting the debate over central bank independence. Growing de-dollarisation, signs of US Treasury-led financial repression and the US mid-term elections warrant caution on the US dollar. Other risks include further Middle East escalation, energy price pressures, softer labour markets and consumer spending, and weaker-than-expected AI returns.
  • Overall, the backdrop remains constructive for risk assets. After a mid-year soft patch, the global economy appears set for a stronger finish to the year, with Europe especially well placed heading into Q4.

Icon

Chart of the quarter

Confidence returns as momentum rebuilds
After a soft patch earlier in the year, business sentiment has recovered across major economies. While risks remain, improving confidence points to a broader and more durable upswing in growth heading into year end.
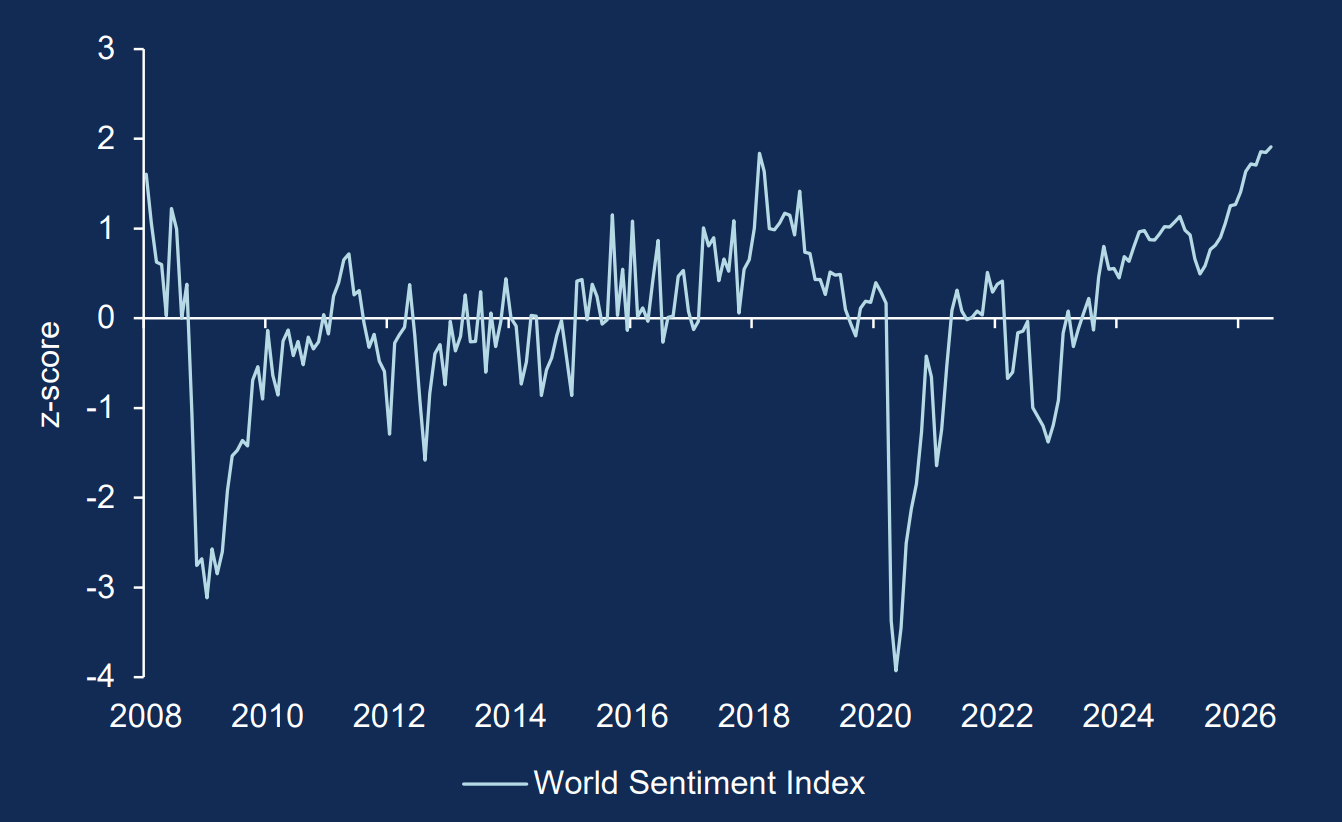
Line chart showing the World Sentiment Index from 2008 to July 2026. Sentiment fluctuates around zero, with sharp declines during the 2008 financial crisis and in 2020, followed by a sustained recovery to nearly 2 in 2026.

Note: The World Sentiment Index quantifies overall sentiment by considering the occurrence of positive and negative words in the Economist Intelligence Unit country reports.
Source: Allianz Global Investors Global Economics & Strategy, Ahir/Bloom/Furceri (data as at 31 July 2026).

Short on time? Download the summary of our House View Q4.
Asset class convictions

Asset class convictions: equities

  • The AI opportunity set is continuing to broaden beyond GPUs as deployment and agentic applications reshape the physical infrastructure of computing, while rising rack density and the limits of copper are driving demand for optical interconnects, advanced materials and power systems.
  • Electrification also remains supported by data-centre build-out, improving industrial orders and infrastructure spending.
  • Across Asia, hardware suppliers may benefit from architecture upgrades and component scarcity, while China’s deep supply chains are supporting AI diffusion across infrastructure, models and applications.
  • India continues to combine an aspirational, consumption led economy with favourable geopolitical positioning and a rapidly developing AI ecosystem. In Japan, Prime Minister Sanae Takaichi’s pro-growth economic policy and corporate governance reforms are providing additional support.
  • Value stocks can enhance portfolio diversification. Attractive relative valuations in an environment of higher nominal and real rates may offer upside. Value’s different sector and factor exposures also provide a potential counterweight to crowded AI, momentum and long-duration growth positions.

The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actualresults, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to updateany forward-looking statement.

Asset class convictions: fixed income

  • We expect the yield curve to steepen in the US, Germany and Australia. US Treasury Inflation-Protected Securities (TIPS) should outperform given ongoing upward pressure on energy prices.
  • At the short end of the curve, German Bunds may offer better value than US Treasuries. At the long end, UK Gilts look attractive relative to other major bond markets. With yields at multi-year highs, we believe investors are well compensated for the fiscal risks.
  • In emerging markets, we prefer bonds issued by oil exporters over importers. We continue to like Brazilian and Hungarian local bonds despite strong year-to-date performance.
  • Against a broadly neutral outlook for the US dollar, we prefer currency pairs that are less dependent on the direction of the US dollar. We favour pro-cyclical and high yielding currencies, financing these positions through selective low-yielding currencies.
  • We continue to see carry as the key driver of credit returns. We are constructive on financials and consumer non cyclicals, cautious on cyclical consumer names, and increasingly positive on selective AI hyperscalers, where recent spread widening has improved valuations.

The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.

Asset class convictions: multi asset

  • We are overweight equities, with our strongest conviction in emerging markets, then Japan, US equities and Europe. This reflects robust earnings growth, positive revisions and continued AI-related capex. Robotics, biotech and gold miners offer attractive thematic opportunities.
  • We are neutral to cautious on developed market government bonds due to sticky core inflation, fiscal concerns, central bank independence questions and priced in rate hikes. We prefer European government bonds but remain cautious on France given election risk.
  • We see value in emerging market bonds, particularly where real yields are high and fiscal conditions favourable. Energy exporting emerging markets are particularly attractive. Our credit stance is broadly neutral, preferring higher-quality investment-grade exposure.
  • Our currency outlook is neutral, with no strong directional views in the short term, while in the medium to long term we expect the US dollar to weaken versus G7 currencies.
  • Investor demand, fiscal concerns and questions over central bank independence keep us constructive on gold. We also favour broader commodities, supported by supply constraints, refinery disruptions and tight energy markets.

The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.

Our latest thinking on macroeconomics and markets, plus high-conviction ideas from our asset class CIOs.

Our full House View includes comprehensive analysis and proprietary data on investment markets.
Download PDF
This is a summary of our House View Q4 2026
Download PDF

This document reflects the views of Allianz Global Investors’ investment leadership going into Q4 2026. Past performance doesnot predict future returns. The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management’s current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.

Investing involves risk. The value of an investment and the income from it may fall as well as rise and investors might not get back the full amount invested.

Past performance does not predict future returns. If the currency in which the past performance is displayed differs from thecurrency of the country in which the investor resides, then the investor should be aware that due to the exchange rate fluctuations the performance shown may be higher or lower if converted into the investor’s local currency.

This is for information only and not to be construed as a solicitation or an invitation to make an offer to buy or sell any securities. The views and opinions expressed herein, which are subject to change without notice, are those of the issuer or its affiliated companies at the time of publication. The data used is derived from various sources and assumed to be accurate and reliable at the time of publication, but it has not been independently verified; its accuracy or completeness is not guaranteed and no liability is assumed for any direct or consequential losses arising from its use, unless caused by gross negligence or willfulmisconduct. The duplication, publication, extraction or transmission of the contents, irrespective of the form, is not permitted, except for the case of explicit permission by Allianz Global Investors.

This material has not been reviewed by any regulatory authorities.


This document is being distributed by the following Allianz Global Investors companies: In Australia, this material is presentedby Allianz Global Investors Asia Pacific Limited (“AllianzGIAP”) and is intended for the use of investment consultants and other institutional/professional investors only, and is not directed to the public or individual retail investors. AllianzGIAP is not licensed to provide financial services to retail clients in Australia. AllianzGIAP is exempt from the requirement to hold an Australian Foreign Financial Service License under the Corporations Act 2001 (Cth) pursuant to ASIC Class Order (CO 03/1103) with respect to the provision of financial services to wholesale clients only. AllianzGIAP is licensed and regulated by Hong Kong Securities and Futures Commission under Hong Kong laws, which differ from Australian laws; in the European Union, by Allianz Global Investors GmbH, an investment company in Germany, authorized by the German Bundesanstaltfür Finanzdienstleistungs-aufsicht(BaFin) and is authorized and regulated in South Africa by the Financial Sector Conduct Authority; in the UK, by Allianz GlobalInvestors (UK) Ltd. company number 11516839, authorised and regulated by the Financial Conduct Authority (FCA); in Switzerland, by Allianz Global Investors (Schweiz) AG, authorised by the Swiss financial markets regulator (FINMA); in HK, by Allianz Global Investors Asia Pacific Ltd., licensed by the Hong Kong Securities and Futures Commission; in Singapore, by Allianz Global Investors Singapore Ltd., regulated by the Monetary Authority of Singapore [Company Registration No. 199907169Z]; in Japan, by Allianz Global Investors Japan Co., Ltd., registered in Japan as a Financial Instruments Business Operator [Registered No. The Director of Kanto Local Finance Bureau (Financial Instruments Business Operator), No. 424], Member of Investment Management Associationof Japan and Type II Financial Instruments Firms Association; in mainland China, it is for Qualified Domestic Institutional Investors scheme pursuant to applicable rules and regulations and is for information purpose only; in Taiwan, by Allianz Global Investors Taiwan Ltd., licensed by Financial Supervisory Commission in Taiwan; in Indonesia, by PT. Allianz Global Investors Asset Management Indonesia licensed by IndonesiaFinancial Services Authority (OJK); and in the Abu Dhabi Global Market by Allianz Global Investors Middle East Limited, which is authorised and regulated by the ADGM Financial Services Regulatory Authority with Financial Services Permission number 250070.

Admaster: 5921168

House View archives

The global economy is bending under successive shocks, but not breaking. Our base case is resilience, but with a range of possible outcomes, selectivity matters.

Discover more

Global markets enter the second quarter navigating a more complex backdrop than many expected at the start of the year. Growth slows yet stays resilient; sticky inflation could delay rate cuts and keep policy tight. We prioritise selective duration, quality carry, AI linked equities and remain cautious on the US dollar.

Discover more

The global economy enters 2026 bending but not breaking. We expect growth to stay on track, creating an environment that favours risk-taking. Expect a resilient yet complex year where active management will be critical.

Discover more

Allianz Global Investors

You are leaving this website and being re-directed to the below website. This does not imply any approval or endorsement of the information by Allianz Global Investors Asia Pacific Limited contained in the redirected website nor does Allianz Global Investors Asia Pacific Limited accept any responsibility or liability in connection with this hyperlink and the information contained herein. Please keep in mind that the redirected website may contain funds and strategies not authorized for offering to the public in your jurisdiction. Besides, please also take note on the redirected website’s terms and conditions, privacy and security policies, or other legal information. By clicking “Continue”, you confirm you acknowledge the details mentioned above and would like to continue accessing the redirected website. Please click “Stay here” if you have any concerns.